

How to Finance Home Exterior Renovations in 2026
Table of Contents
Step 1: Determine What Your Exterior Renovation Will Cost
Step 2: Compare Home Renovation Financing Options
Cash-Out Refinancing and Mortgage Refinancing
Construction Loans and Hard Money Loans
Step 3: Evaluate a Home Equity Loan for Renovations
Home Equity Loan vs. HELOC: Which Fits Your Project?
Step 4: Understand Contractor Financing Plans
Step 5: Explore Roof Replacement Financing and Other Project-Specific Loans
Matching the financing path to the project
Roof replacement financing
FHA Title I property improvement loans
Energy-efficient mortgages
Rebates, incentives, and utility programs
How to choose when the project is urgent
Step 6: Review Total Borrowing Costs and Repayment Scenarios
A worked example
How to run your own comparison
The closing-cost trap
Variable-rate risk on HELOCs
Factoring in the tax treatment
Step 7: Avoid Common Mistakes When Financing Exterior Renovations
Conclusion: Matching Your Project to the Right Funding Source
Frequently Asked Questions
Last Updated: October 7, 2026
Step 1: Determine What Your Exterior Renovation Will Cost
The first step in financing home exterior renovations is knowing your real number, not a guess, but a written estimate.
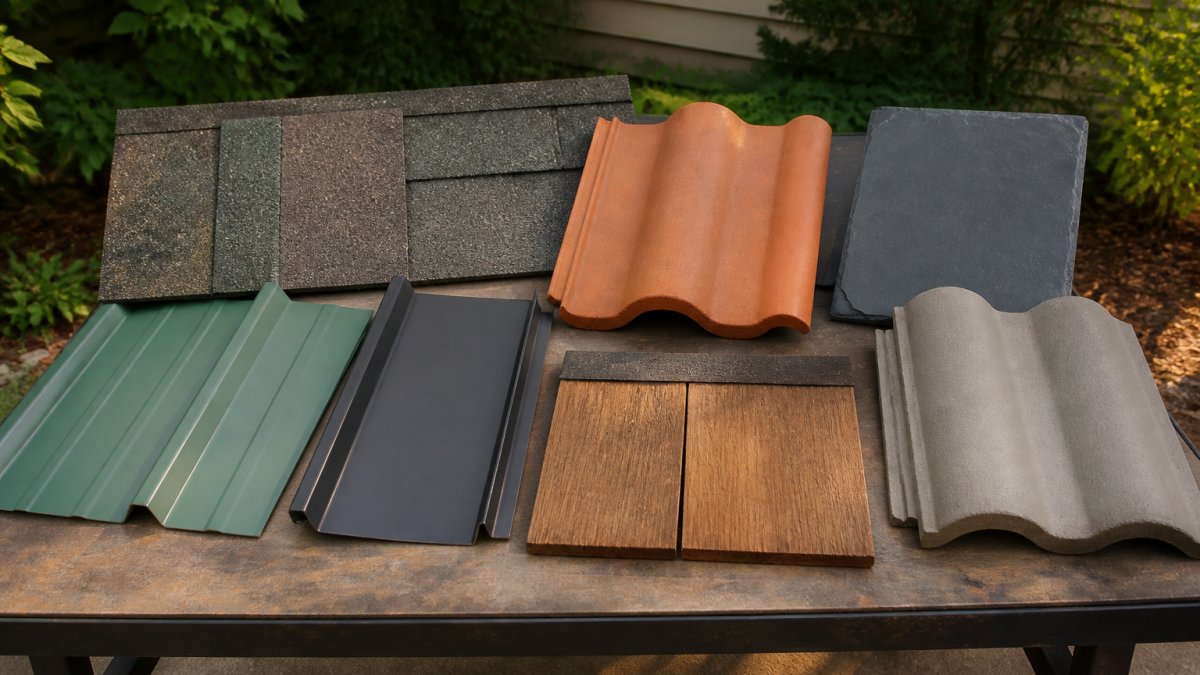
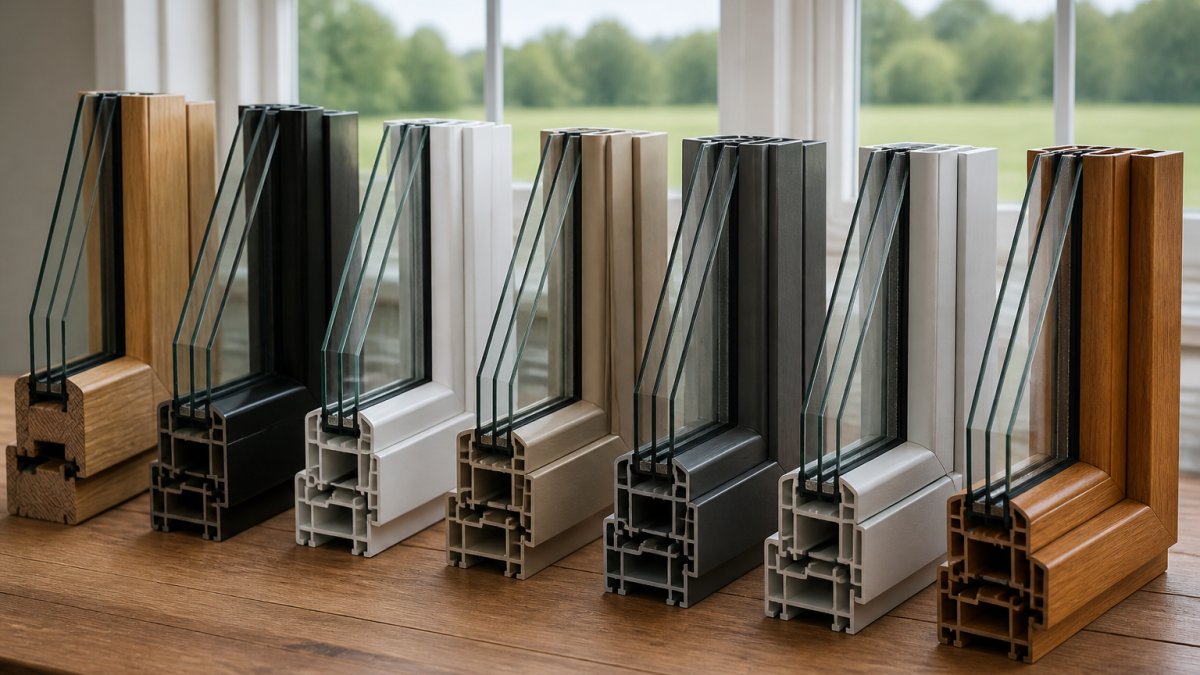
Exterior renovations cover roofing, siding, windows, doors, decks, driveways, and landscaping, each with its own cost drivers: a roof depends on square footage and material, siding on wall area and insulation, windows on count, size, and frame type.
Here is what to collect before you shop for money:
Written contractor estimates for each part of the project
Permit fees from your local building office
A contingency fund of 10 to 20 percent for surprises
Watch Out Skipping permits is a costly mistake. Unpermitted exterior work can block a future home sale and may force you to tear out finished work. Always confirm permit requirements before work begins.
Step 2: Compare Home Renovation Financing Options
Home renovation financing options split into two groups: loans secured by your home and loans that are not. Secured options cost less but put your property on the line; unsecured options are faster and safer for your home but charge higher rates.
Option | Best For | Secured by Home? | Typical Speed |
Cash savings | Small projects under your budget | No | Immediate |
Personal loan | Quick, mid-size projects | No | A few days |
Home equity loan | Larger projects, fixed budget | Yes | 2-4 weeks |
HELOC | Staged or phased work | Yes | 2-4 weeks |
Cash-out refinance | Big projects plus rate change | Yes | 4-6 weeks |
Construction loan | Major structural work | Yes | 6-10 weeks |

Cash-Out Refinancing and Mortgage Refinancing
A cash-out refinance replaces your mortgage with a larger one and hands you the difference in cash. It works best when you also lower your rate. If rates have risen since you bought, it may raise your monthly payment, so run the numbers first.
Construction Loans and Hard Money Loans
A construction loan funds work in stages; a construction-permanent loan rolls into a standard mortgage when done. Hard money loans are fast but charge high rates and fees, suiting investors more than homeowners.
Step 3: Evaluate a Home Equity Loan for Renovations
A home equity loan for renovations gives you a lump sum at a fixed rate, repaid in equal monthly payments over a set term, the cleanest fit when you know your project cost and want a predictable bill.
Eligibility usually depends on three things:
Your credit score
Your combined loan-to-value ratio
Your debt-to-income ratio
Lenders typically want you to keep at least 15 to 20 percent equity after borrowing. Closing costs apply, so ask for a full cost sheet, not just the rate.
Home Equity Loan vs. HELOC: Which Fits Your Project?
A home equity line of credit (HELOC) works like a credit card tied to your home: draw as needed and pay interest only on what you use. That makes it better for phased work, like siding this fall and a roof next spring, while a home equity loan wins for one fixed price and a fixed payment.
Pro Tip If your project will be built in stages, ask your lender whether interest-only draw periods are available on a HELOC. It keeps payments low while the work is underway.
Step 4: Understand Contractor Financing Plans
Contractor financing plans let you pay through a lender the contractor partners with: you apply, get approved, and the lender pays the contractor directly. Payments are often monthly, and some plans offer no-interest promotional periods if you pay in full by a set date.
These plans are convenient, but read the fine print. Deferred-interest offers can charge retroactive interest on the full balance if you miss the payoff date.
Confirm who holds the loan after signing
Ask whether the rate is fixed or adjustable
Check for prepayment penalties
Step 5: Explore Roof Replacement Financing and Other Project-Specific Loans
Not every exterior project fits the same funding mold. A leaking roof is an emergency; a deck planned for next summer is not. Project size, urgency, and energy performance all change which financing path makes sense, and most general guides list options without matching them to the job.
Matching the financing path to the project
Project | Typical urgency | Financing that tends to fit best |
High, leaks worsen fast | Contractor-offered specialty loan, personal loan, or HELOC if you already have one open | |
Siding replacement | Medium | Home equity loan (fixed scope, fixed price) |
Window replacement | Medium, often phased | HELOC for phased work; energy-efficient mortgage if bundled with other upgrades |
Deck or patio build | Low to medium | Personal loan or home equity loan |
Driveway or hardscape | Low | Cash savings or personal loan |
Landscaping and curb appeal | Low, often staged | Cash savings or HELOC draw as work progresses |
Roof replacement financing
Roofing is the most common exterior emergency and the project most likely to be financed through the contractor. Many roofing companies partner with a specialty lender, approving you in minutes and paying the crew directly.
With equity and time, a home equity loan or HELOC usually beats a contractor loan on rate. If the roof is failing now and you cannot wait weeks for underwriting, the contractor path may be worth the higher cost.
FHA Title I property improvement loans
The Federal Housing Administration's Title I program insures loans from approved lenders for property improvements, including exterior work (Title I Insured Programs). Key features:
The loan is unsecured for smaller amounts and can be secured for larger ones.
It is available to owner-occupants and to investors for certain property types.
Maximum loan amounts and terms are set by the program and updated periodically, so confirm current limits with an FHA-approved lender.
Title I is worth asking about if your credit is imperfect or you would rather not tap home equity.
Energy-efficient mortgages
An energy-efficient mortgage (EEM) folds efficiency improvements, insulation, windows, doors, roofing with better thermal performance, into a home purchase or refinance loan, financing upgrades at mortgage rates rather than consumer-loan rates. The catch: EEMs are tied to a purchase or refinance, so they are not standalone options if you already own your home and do not want to refinance.
Rebates, incentives, and utility programs
Utility companies and state housing agencies frequently offer rebates or low-interest loan programs for efficiency-related exterior work. These change often and vary widely by location. Check the U.S. Department of Energy's homeowner resources for current federal, state, and utility programs before you borrow, a rebate you did not know about can shrink the amount you need to finance.
Pro Tip Stack your funding. A common pattern is to use a rebate or utility incentive to cover part of the cost, then finance only the remainder. Borrowing less always costs less.
How to choose when the project is urgent
If the work cannot wait, an active leak, a failed window, storm damage, prioritize speed of approval over the lowest rate. A personal loan or contractor-arranged loan can fund in days; a home equity loan takes two to four weeks, and a cash-out refinance four to six. Match the timeline to how long you can safely wait.
Step 6: Review Total Borrowing Costs and Repayment Scenarios
The interest rate is not the full cost. Total borrowing cost includes the rate, closing costs, fees, and term length, two loans with the same rate can cost very different amounts if one runs five years longer. Here is what that looks like in numbers.
A worked example
Say you need $25,000 for a roof and siding project. These three common funding paths are illustrative, your actual rate depends on your credit, equity, and lender, but the pattern holds.
Option | Amount | Rate | Term | Monthly payment | Total interest paid |
Personal loan | $25,000 | 12% | 5 years | ~$556 | ~$8,400 |
Home equity loan | $25,000 | 8% | 10 years | ~$303 | ~$11,400 |
HELOC (drawn and repaid) | $25,000 | 9% variable | 10 years | Varies with prime rate | Varies, can rise or fall |
Notice the trade-off: the personal loan has the highest monthly payment but the lowest total interest because the term is short, while the home equity loan has the lowest monthly payment but costs more overall over ten years instead of five.
How to run your own comparison
Get the monthly payment for each option at your actual quoted rate and term.
Multiply the monthly payment by the number of months.
Subtract the amount you borrowed.
That difference is your true cost of borrowing, before closing costs.
Add closing costs (home equity loans and HELOCs typically carry them; personal loans usually do not).
Compare the totals side by side.
The closing-cost trap
A home equity loan at 8% can look cheaper than a personal loan at 12%, until you add closing costs, which often run into the low thousands depending on lender and location. On a small project, those costs can erase the rate advantage, so always ask for a full cost sheet and compare the all-in number.
Variable-rate risk on HELOCs
A HELOC rate is usually tied to the prime rate, which moves with Federal Reserve policy decisions. When rates rise, your payment rises, sometimes with little warning. Ask the lender:
What is the margin over prime?
Is there a cap on how high the rate can go, and how often can it adjust?
What happens to my payment if the rate rises two percentage points?
A fixed-rate home equity loan removes that uncertainty. A HELOC gives you flexibility but transfers interest-rate risk to you.
Factoring in the tax treatment
Interest on a home equity loan or HELOC may be deductible if the proceeds buy, build, or substantially improve the home securing the loan (Real estate (taxes, mortgage interest, points, other property expenses) 2). The rules are specific and have changed in recent years, so confirm your situation with a tax professional. Personal loan interest is generally not deductible.
Key Takeaway A lower monthly payment often means a longer term and more total interest. Always compare loans on total cost, including closing costs, not just the monthly bill or the headline rate.
Step 7: Avoid Common Mistakes When Financing Exterior Renovations
The biggest mistake is borrowing before you have a fixed scope. Lenders approve based on numbers, and a vague project invites a vague loan.
Other errors we see often:
Skipping the contingency fund, then running short mid-project
Choosing the lowest rate without checking fees
Tying up all your home equity and leaving no cushion
Some exterior improvements can raise your home's insured value, which may change your premium. Ask your insurer before work starts.
Conclusion: Matching Your Project to the Right Funding Source
Financing exterior upgrades comes down to one question: how much certainty do you have?
Once you know your number, Xperienced can help you get there. We are a veteran-owned company offering expert installation of windows, roofing, doors, and siding, plus financing options and strong warranties on all work.
Get a quote with Xperienced and start your exterior renovation with a clear plan and a payment path that fits your budget.
Frequently Asked Questions
What financing options are available for exterior home renovations?
Homeowners can choose from several financing options for exterior renovations, including home equity loans, HELOCs, cash-out refinancing, personal loans, and contractor financing plans. Each option has different interest rates, repayment terms, and eligibility requirements. Home equity loans offer fixed rates and predictable payments, while HELOCs provide flexible borrowing. Personal loans work for smaller projects but carry higher rates. Contractor financing plans may offer promotional rates. Compare at least three offers before committing.
Should I use a home equity loan or a personal loan for renovations?
A home equity loan for renovations typically offers lower interest rates because it uses your home as collateral. Personal loans are unsecured, so they carry higher rates but do not put your home at risk. For larger exterior projects like roof replacement or siding, a home equity loan usually makes more sense. For smaller projects under $10,000, a personal loan may be faster and simpler. Your credit score and existing home equity will determine which option you qualify for.
How do contractor financing plans work?
Contractor financing plans are payment arrangements offered through a remodeling company, often in partnership with a lending institution. These plans may include promotional periods with low or zero interest, followed by standard rates. Approval is usually faster than traditional bank loans. However, always read the terms carefully. Check whether the rate is fixed or adjustable, what happens after any promotional period ends, and whether there are prepayment penalties. Compare contractor financing plans against direct lender offers before deciding.
Can I finance a roof, siding, or window replacement?
Yes. Roof replacement financing, siding, and window projects can all be funded through home equity loans, HELOCs, personal loans, or contractor financing plans. Some lenders offer specific renovation loan products backed by government programs that allow higher loan amounts for energy-efficient upgrades. If your project includes energy-efficient windows or insulation, you may qualify for better terms. Get contractor estimates first, then match the total project cost to the financing option with the lowest total borrowing cost.
GET A QUOTE
Comments